Hey, Massachusetts drivers! Ever wondered how much you might be shelling out for auto insurance in the Bay State? Whether you’re cruising down the scenic roads of Cape Cod or navigating the bustling streets of Boston, understanding the ins and outs of auto insurance can save you a bundle. Get ready to discover everything you need to know about auto insurance in Massachusetts with our comprehensive guide!
Let’s dive into the nitty-gritty of auto insurance in Massachusetts. From the basic requirements to the factors that influence your premiums, we’ve got you covered. We’ll even throw in some nifty tips on how to keep those costs in check. So buckle up, as we embark on this journey to help you get the best bang for your buck on your auto insurance policy!
Overview of Auto Insurance in Massachusetts
Did you know that Massachusetts has some of the strictest auto insurance laws in the country? If you’re a driver here, you can’t hit the road without meeting certain requirements. But don’t worry, I’ve got you covered!
In Massachusetts, it’s not just about getting auto insurance—it’s about getting the right coverage. The state mandates that all drivers have a minimum level of coverage, including Bodily Injury, Property Damage, Personal Injury Protection, and Uninsured Motorist Coverage. These requirements are designed to protect you and others on the road.
Types of Auto Insurance in Massachusetts
When it comes to auto insurance in Massachusetts, you’ve got options. Beyond the minimums, there are several types of coverage to consider. These include comprehensive, collision, and optional bodily injury coverage. Each type of insurance serves a different purpose, and knowing the difference can save you a ton of headache—and money—in the long run.
Here is the deal: while comprehensive coverage protects against non-collision-related incidents like theft or natural disasters, collision coverage is what saves you when your car hits—or is hit by—another object. Want to go the extra mile? Consider optional bodily injury coverage. It can help cover the cost if you’re at fault in an accident.
Pro Tip: Always compare multiple insurance providers before committing. A little homework can lead to significant savings.
The Importance of Auto Insurance for Drivers in Massachusetts
Auto insurance isn’t just a legal requirement—it’s your financial safety net. Imagine getting into an accident and having to pay out of pocket! With Massachusetts being a no-fault state, personal injury protection (PIP) covers medical expenses regardless of who is at fault. This coverage is invaluable and can mean the difference between financial stability and ruin.
But there’s more. Auto insurance also provides peace of mind. Knowing that you and your loved ones are protected if something goes wrong is invaluable. Massachusetts drivers understand this and tend to have more comprehensive coverage than the national average.
Factors Affecting Auto Insurance Costs

Ever wonder why auto insurance premiums seem to vary wildly from person to person? The truth is, several factors are at play. These elements make the insurance market a complex beast, especially in Massachusetts.
You might be surprised to learn how much your age, driving history, or even the type of car you drive can affect your rates. Let’s dive into the nitty-gritty details.
Demographics: Age, Gender, and Marital Status
Did you know that young drivers often pay more for auto insurance? It’s true. Insurance companies consider them high-risk, and their rates reflect that. Meanwhile, married individuals tend to enjoy lower premiums. Why? Because they are statistically safer drivers.
Gender also plays a role. For instance, young males are usually charged higher premiums compared to their female counterparts. It’s all about risk assessment, and unfortunately, stats show that young men are involved in more accidents.
The Role of Driving History
Your driving history can either make or break your premium costs. Have a clean record? Congratulations, you’re likely to get a better rate. But if you’ve had accidents or violations, expect to pay more.
Insurance companies are all about minimizing risk. A spotless driving history paints you as a low-risk client, while a record full of infractions does the opposite.
Vehicle Type and Its Impact
The type of car you drive is another major factor in determining your insurance premiums. A sports car may look cool, but it often comes with a higher insurance bill. Why? Because they’re typically driven faster and are more costly to repair.
On the other hand, family-friendly SUVs usually mean lower rates. They are deemed safer and often have a range of safety features.
Pro Tip: Consider opting for a car with high safety ratings and features. This often results in lower premiums.
Average Costs of Auto Insurance
How much are you paying for auto insurance? If you’re in Massachusetts, your wallet might be getting a workout. Believe it or not, the average cost of auto insurance here is one of the highest in the nation!
But why are rates so high, and how do they vary across the state? Let’s break it down.
City-by-City Cost Comparison
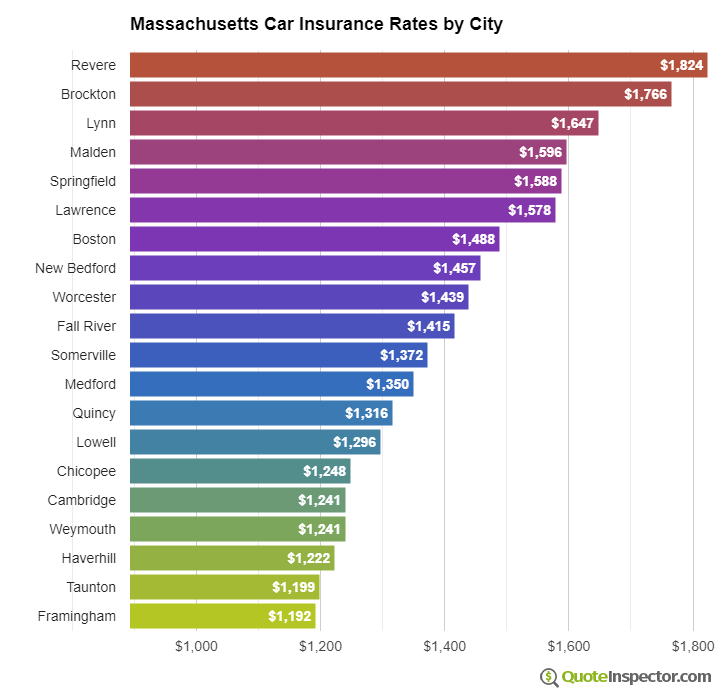
Where you live in Massachusetts can heavily impact your auto insurance costs. Urban areas like Boston typically see higher premiums compared to rural areas. Here’s a closer look:
| City/Region | Average Annual Premium |
|---|---|
| Boston | $2,100 |
| Worcester | $1,800 |
| Springfield | $1,700 |
| Lowell | $1,600 |
| Cape Cod Area | $1,500 |
As you can see, living in a bustling city like Boston can cost you an extra few hundred dollars annually. BUT here’s the deal: these rates can fluctuate based on a myriad of factors.
Recent Pricing Trends
Insurance prices haven’t been static. Over the last few years, there’s been a steady climb in premiums. Why? Rising repair costs and increased traffic congestion are major culprits. In fact, Massachusetts saw an average rate increase of about 4% annually from 2018 to 2023.
Pro Tip: If you’re seeing steep hikes, shop around and compare policies. Even a small percentage change can mean significant savings.
Understanding these trends can help you make informed decisions when it comes to renewing your policy. Knowledge is power, but in this case, it’s also money saved.
How to Save on Auto Insurance
Did you know that the average American spends over $1,500 a year on auto insurance? That’s a huge chunk of change. BUT what if I told you that you could slash this cost without sacrificing coverage?
Let’s dive into some actionable strategies to reduce your auto insurance costs in Massachusetts. We’ll cover everything from seeking out discounts to boosting your credit score.
Snag Discounts for Safe Driving and Other Smart Moves
Safe drivers are the heroes in the eyes of insurance companies. If you have a clean driving record, you can often qualify for significant discounts. Think 10% or more off your premium. Insurance companies also love it when you bundle your auto insurance with other policies, like home or renters insurance. This combo could net you another sweet discount.
Installing safety devices in your car is another savvy move. Gadgets like anti-theft devices and advanced braking systems can score you even more savings. Why? Because you lower the risk of accidents and theft.
Pro Tip: Always ask your insurer about any lesser-known discounts. Sometimes they offer reductions for things like being a member of certain organizations or even good grades if you’re a student.
Boost Your Credit Score for Better Rates
Here is the deal: your credit score affects your insurance premium. Crazy, right? But insurers see a high credit score as a sign of reliability, which means less risk for them. So, improving your credit score could lead to lower premiums.
Step #1, check your credit report for errors and get them fixed. Step #2, keep credit card balances low and pay bills on time. Step #3, avoid opening too many new accounts at once.
By following these steps, you can improve your credit score over time, potentially leading to hefty savings on your auto insurance bill.
Choosing the Right Auto Insurance Provider
Ever felt overwhelmed by the sheer number of auto insurance options out there? You’re not alone. Picking the right insurance provider is critical. It can save you money, provide peace of mind, and offer the protection you need when you need it most.
The key lies in evaluating coverage, customer service, and financial stability. You might find yourself drowning in fine print and ratings. BUT here’s the deal: if you know what to look for, it’s a game-changer.
Evaluating Coverage Options
When choosing an insurance provider, start by comparing the coverage options. Does the insurance meet your needs? Consider liability, comprehensive, and collision coverage. Each type gives different levels of protection. Make sure to choose a plan that fits your driving habits and financial situation.
Next, dive into any extras offered, like roadside assistance or rental reimbursement. More coverage can mean more peace of mind.
Understanding Customer Service Quality
Customer service can make or break your experience with an insurer. Look at how easy it is to file claims or contact support. A company with 24/7 assistance is a huge plus.
Pro Tip:
Read customer reviews to get a feel for the company’s service quality. A provider with high ratings in customer satisfaction is often a safer bet.
Financial Stability and Ratings
The financial health of an insurance company is crucial. Why? You want them to be able to pay out claims when necessary. Use ratings from agencies like A.M. Best or Moody’s as indicators of a company’s stability.
Keep in mind that a financially strong insurer is less likely to go under, leaving you in a lurch.
Comparison of Top Auto Insurance Providers in Massachusetts
Here’s a quick look at some of the top auto insurance providers in Massachusetts. Check their coverage, customer service, and ratings before making a decision:
| Provider | Coverage Options | Customer Service Rating | Financial Stability |
|---|---|---|---|
| Provider A | Comprehensive, Collision, Liability | 4.5/5 | A+ |
| Provider B | Liability, Roadside Assistance | 4/5 | A |
| Provider C | Full Coverage, Rental Reimbursement | 3.5/5 | A- |
The Importance of Reading Reviews and Ratings
Why bother with reviews? They offer real insights from actual customers. Reviews can highlight areas where a provider excels or lags. Are claims processed quickly? Is the customer service responsive?
Check multiple sources and compare experiences to get a balanced view. In the end, these ratings can guide you toward the most reliable choice.
Legal Aspects of Auto Insurance in Massachusetts
Did you know that Massachusetts has some of the toughest auto insurance laws in the U.S.? If you’re driving in the Bay State, you need to be well-informed about these regulations.
Massachusetts law requires every driver to carry a minimum level of insurance coverage. This includes $20,000 per person and $40,000 per accident for bodily injury, $5,000 for property damage, and additional coverages like Personal Injury Protection.
Mandatory Insurance Coverage Requirements
In Massachusetts, you can’t just hit the road without insurance. The law is crystal clear: you must have at least four types of coverage. This includes bodily injury liability and property damage liability. But here’s the deal, opting for only the minimum coverage might leave you exposed. It’s wise to consider adding collision or comprehensive coverage to protect your assets.
Penalties for Not Maintaining Proper Auto Insurance
Think you’ll get away with skipping insurance? Think again. The penalties are harsh. You could face fines, license suspension, and hefty surcharges. Plus, driving uninsured can lead to a criminal record, which no one wants. The cost of non-compliance can far outweigh the price of a premium.
Impact of Recent Legislative Changes
Recently, Massachusetts has tightened the screws even more with new legislative changes. These updates have streamlined claims processes and introduced stricter penalties for fraud. While they aim to reduce insurance costs, they also mean that drivers need to stay vigilant about their coverage and premiums.
Pro Tip: Stay ahead of the curve by regularly reviewing your policy in light of recent legal changes. It could save you money and headaches down the road!
Conclusion
And there you have it! Navigating the world of auto insurance in Massachusetts doesn’t have to be a daunting task. By understanding the factors that affect your rates and knowing how to leverage discounts and improve your driving profile, you can keep those premiums in check. So go ahead, make an informed choice, and drive with peace of mind. Safe travels!
Q&A
What are the minimum auto insurance requirements in Massachusetts?
In Massachusetts, drivers must carry a minimum of $20,000 per person and $40,000 per accident in bodily injury liability coverage, $5,000 in property damage liability coverage, and personal injury protection (PIP) coverage.
How does age affect auto insurance costs in Massachusetts?
Age is a significant factor in determining auto insurance rates. Younger drivers often face higher premiums due to their lack of experience, while mature drivers may enjoy lower rates as they gain more driving experience.
Can improving my credit score reduce my auto insurance premiums?
Yes, improving your credit score can positively impact your auto insurance premiums. Insurers often consider credit history when calculating rates, as it can indicate a policyholder’s risk level.
What discounts are available for safe driving in Massachusetts?
Many insurers in Massachusetts offer discounts for safe driving habits, such as maintaining a clean driving record, completing defensive driving courses, or installing safety features in your vehicle.
How do I choose the right auto insurance provider in Massachusetts?
To choose the right provider, compare coverage options, customer service reviews, and financial stability. It’s also beneficial to read customer reviews and ratings to make an informed decision.
Are there penalties for not having auto insurance in Massachusetts?
Yes, driving without auto insurance in Massachusetts can lead to severe penalties, including fines, license suspension, and even vehicle impoundment.
How has recent legislation impacted auto insurance policies in Massachusetts?
Recent legislative changes can affect policy terms, pricing, and coverage options. It’s crucial to stay informed about these changes to ensure compliance and optimal coverage.
